Recent Economic Triggers and the Potential Bull Run
In the last few days, a lot has happened with the Indian economy as well as the Indian stock markets. The bigger question is: are we likely to see a massive bull run in the Indian stock market right now or not? Whether you invest in mutual funds, ETFs, or Indian stocks, this video is going to help you analyze the cumulative impact of these events. First, let’s look at the recent India–US trade deal where the US has reduced tariffs to 18%. In the news, you will immediately hear that the textile sector or other specific sectors are going to give you massive returns. However, please be very careful right now. Looking at the sector returns at the end of February 3rd, the run-up has already gone over the roof. The textile sector was up 12.67% in just one day, the power sector up 6.99%, construction up 6.28%, shipping up 6.25%, auto ancillary up 6.11%, and metal ferrous up 5.28%. By the time you research these sectors and individual stocks, there is not a lot of valuation comfort remaining. Do not just blindly follow what you hear in the news regarding upcoming sectors. Following the announcement of the US–India trade deal, day-one broad indices—including the Nifty 50, Nifty Next 50, mid-cap, small-cap, and micro-cap—all saw a 2% to 3% run-up in a single day. At the sector level, almost every space including banking, IT, pharma, metal, and energy rallied on the very first day.
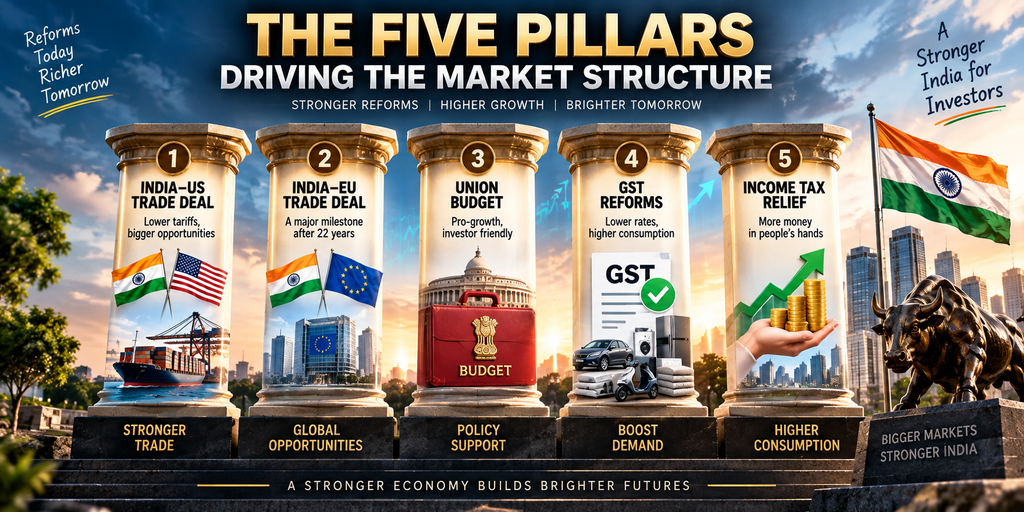
The Five Pillars Driving the Market Structure
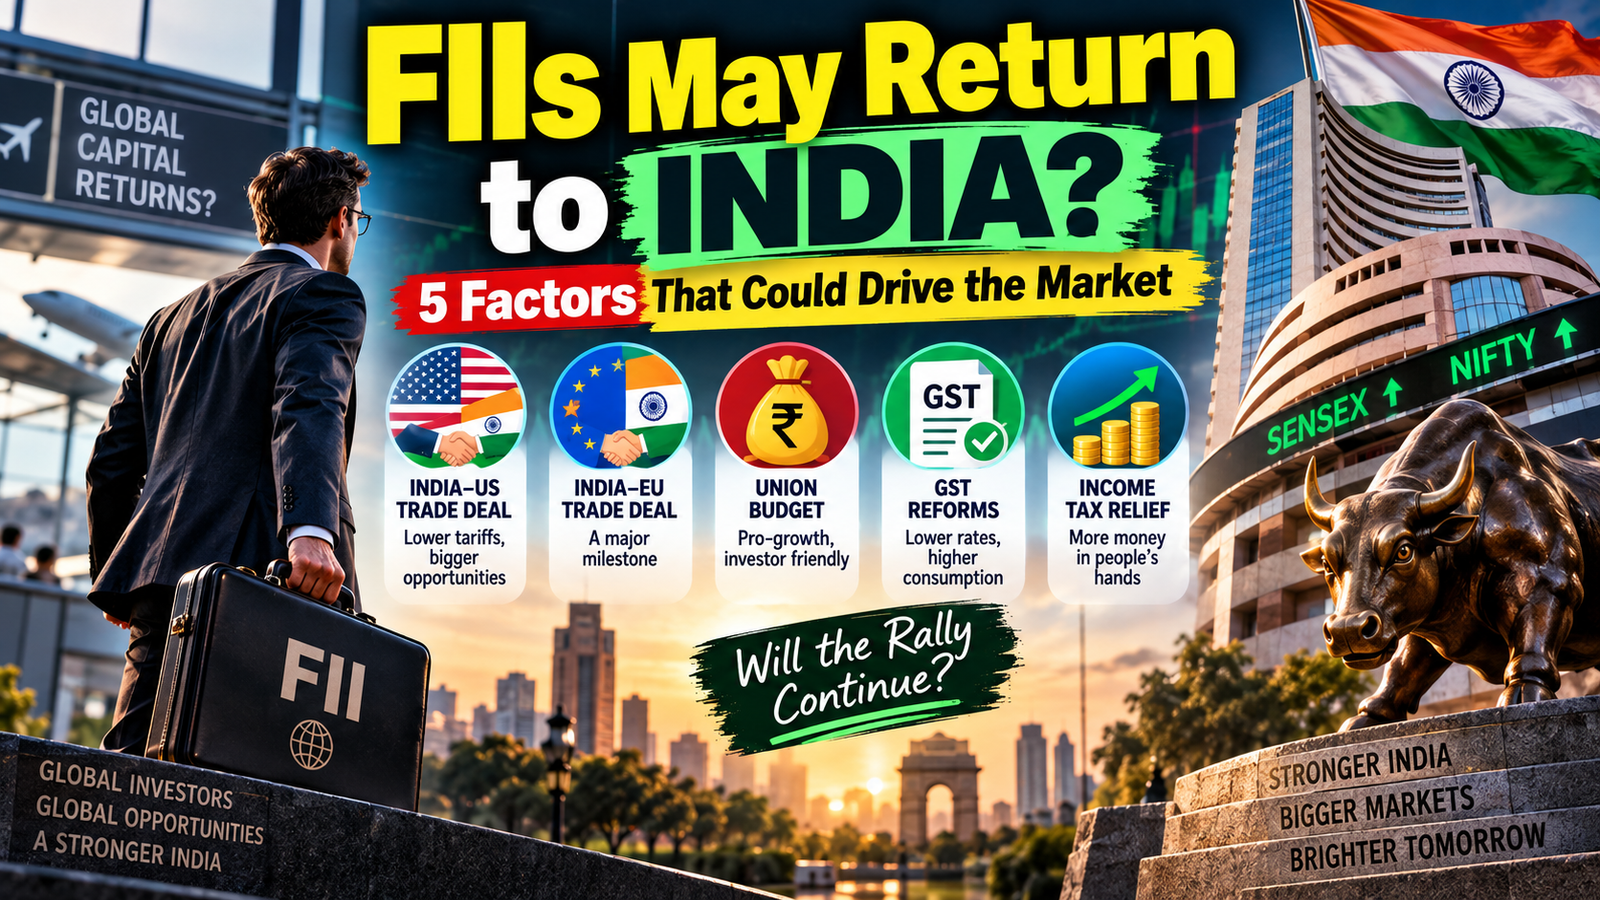
For a massive, sustained bull run or extended rallies to hold, one major thing needs to happen: Foreign Institutional Investors (FIIs) need to return to the Indian stock market. There are currently four to five strong positive signals indicating they might.
- The India–US Trade Deal: The recently announced tariff reductions.
- The India–EU Trade Deal: Signed just ten days prior, this is the “mother of all deals” and a significant milestone that has been in the works for roughly 22 years since 2007. The timing is ideal for FIIs to return.
- The Union Budget: Announced on February 1st, there was a lot of noise surrounding Securities Transaction Tax (STT). However, STT changes will not drive the markets down long-term because Futures and Options (F&O) trading has become an addictive, speculative business; you cannot easily keep participants out of the F&O market, despite marginal impacts on volume. From a structural reform and growth perspective, it was a very positive budget for the economy.
- GST Reforms: The big GST reforms introduced massive relief by slashing rates from 28% down to 18% for sectors like two-wheelers, small cars, TVs, ACs, and cement, while transitioning to a streamlined two-tier GST system. Data shows that GST revenues have not dropped; instead, the rationalized structure makes business operations significantly easier.
5. Income Tax Relief: The income tax slabs were rationalized and reduced up to 12 lakhs previously, providing a strong consumption boost to the economy.
Analyzing FII Behavior and Market Valuations
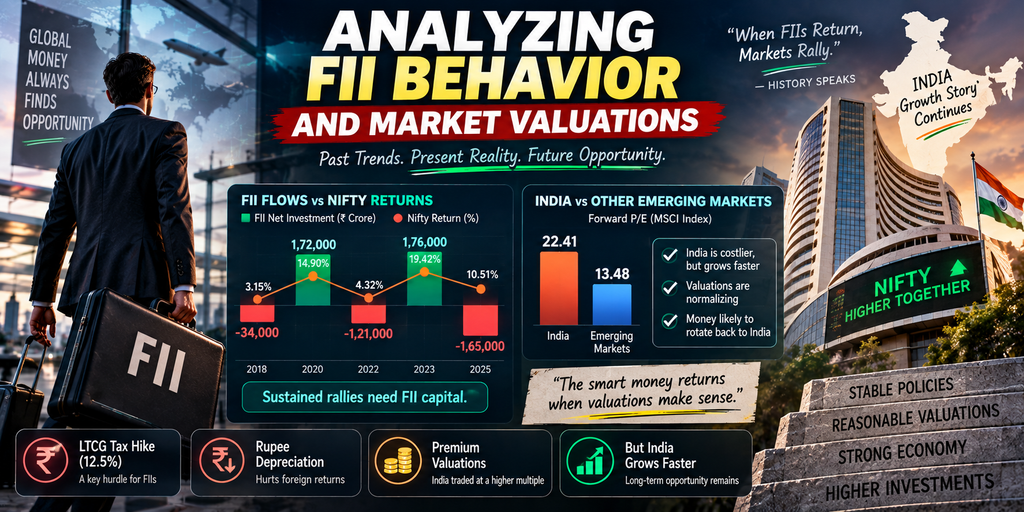
Why focus so heavily on the return of FIIs? The past 10 years of data screams that until FIIs return, we will not see sustained rallies in the Indian stock market. The previous year, 2025, marked the single largest selling period by FIIs in history, pulling out 1,65,000 crores. Despite this massive selling pressure, the Nifty managed a decent return of 10.51% solely due to robust domestic SIP inflows. In comparison, when FIIs sold 1,21,000 crores in 2022, Nifty only gave 4.32% because SIPs were just starting out. When they sold 34,000 crores in 2018, Nifty gave 3.15%. Conversely, when FIIs bought 1,72,000 crores in 2020, Nifty surged by nearly 15%. In 2023, their record investment of 1,76,000 crores drove a 19.42% return. Sizable, sustained bull runs depend heavily on FII capital. Currently, major brokerages project Nifty’s EPS growth to be around 12% to 14% for the year, giving a reasonable forward P/E valuation of around 20.4, which should attract foreign capital. FIIs have stayed away recently due to a few key hurdles: the long-term capital gains tax hike to 12.5%, persistent rupee depreciation which directly hurts foreign investor returns, and premium valuations. The MSCI India Index (representing large and mid-cap companies) sat at a forward P/E of 22.41 as of December 2025, making India costlier than other emerging markets which average a P/E of 13.48. However, India is growing much faster. Given that MSCI India delivered only 9.49% in 2025 compared to the broader emerging markets’ 41%, money is highly likely to rotate back into India as valuations normalize.
Strategies for Mutual Fund and ETF Investors
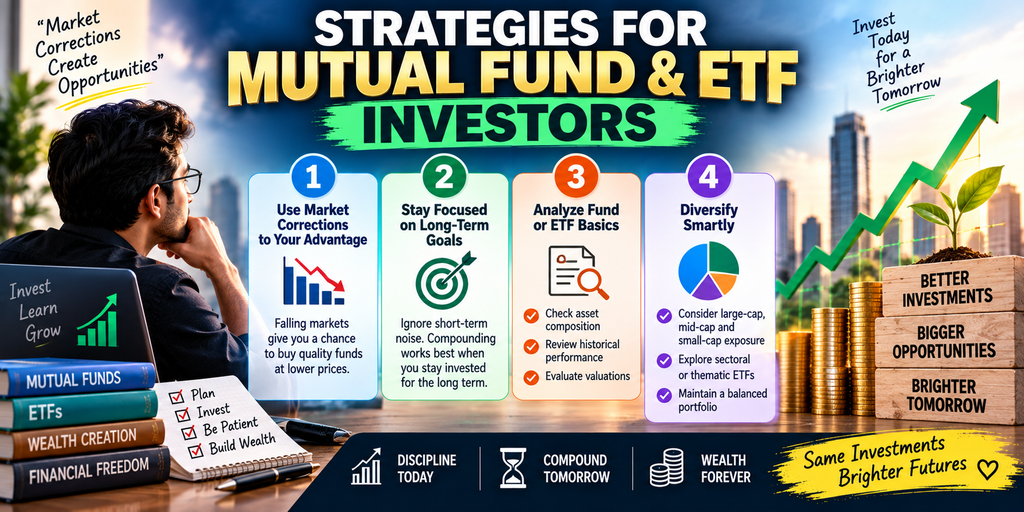
When markets experience pullbacks, it creates direct discount opportunities for long-term investors. Looking at random examples across the board, many large-cap funds have seen their NAV drop roughly 5% from all-time highs due to recent market declines. Mid-cap funds have seen even steeper corrections, with some NAVs dropping 15% to 16% (e.g., correcting from an NAV of 121 down to 105). Small-cap mutual funds are similarly discounted, pulling back from peak NAVs of 285 down to around 256. Buying when the market is down takes courage, but it positions you to enjoy the subsequent rallies rather than scrambling to figure out where to put money after the market has already recovered. There are still plenty of pockets offering great value for long-term investors. For ETF investors, analyzing asset compositions, historical returns, and valuations will highlight similar entry opportunities when they emerge.
Top 3 Sectors for 2026
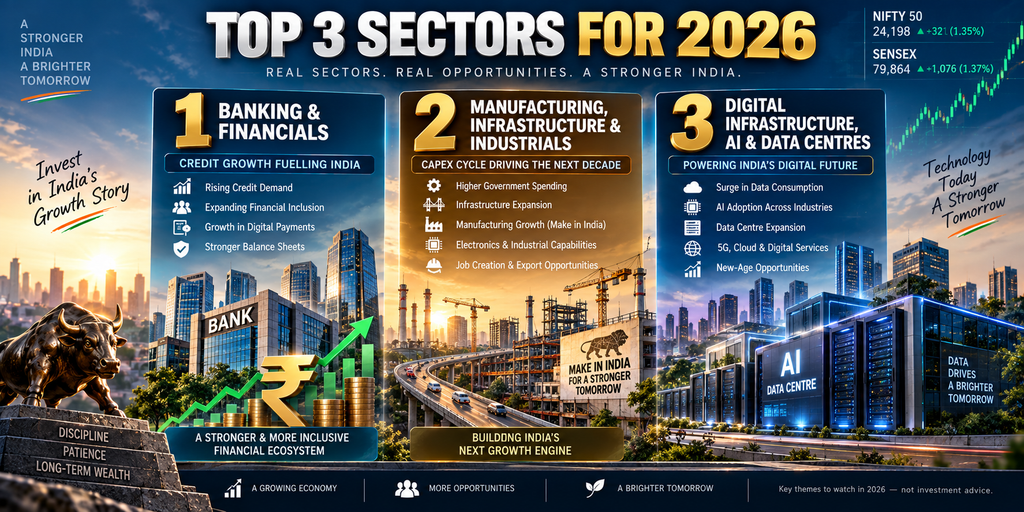
- Auto and Auto Ancillary Sector: This sector features a massive tailwind from the recent GST rate cut from 28% to 18%. January 2026 sales figures show explosive growth: Tata Motors’ passenger vehicle sales shot up by 47%, Mahindra & Mahindra’s SUV sales grew by 24%, and even Maruti Suzuki posted an 11% volume growth. Major manufacturers recorded double-digit growth rates in January 2026. Two-wheeler companies are seeing similar surges, with Hero MotoCorp up 26% and TVS Motors up 29% in sales growth. While the India–EU deal poses a minor long-term risk as import duties on European cars gradually reduce, the immediate operational momentum remains highly positive. Furthermore, auto ancillary companies stand to benefit heavily from the India–US trade deal due to the large volume of component exports to the US.
- Data Centers: This is a vital forward-looking theme targeting 2030 and beyond. The Union Budget formalized a massive tax holiday extending up to the year 2047 for global companies providing data center services through Indian partners. This formalization follows the initial draft policy and cements data centers as a incredibly hot, high-growth sector for the coming years.
- Banking, Financial Services, and Capital Markets: This evergreen sector is structurally driven by India’s core economic growth story. Evaluating companies like Jio Financial Services reveals rapid operational scaling, including 354% growth in their NBFC AUM and 156% YoY growth in payment solutions. For developing financial entities, looking at the Price-to-Book (PB) ratio is much more informative than P/E; Jio Financials’ Price-to-Book has moderated to a comfortable 1.1 against a median of 1.4. Similarly, a banking giant like ICICI Bank is trading right at its 10-year median PB ratio of 2.8. Though its recent quarterly corporate results showed a 4% decline in Profit After Tax (PAT)—causing retail panic and a drop in valuation—the decline was purely due to conservative, proactive standard asset provisioning of 12.83 billion required by the RBI. These provisions impact immediate optics but will eventually roll back into profitability. Meanwhile, capital market firms like Motilal Oswal Financial Services are growing rapidly, showing 16% standalone profit growth and 58% consolidated growth accounting for treasury gains, supported by reasonable valuations relative to their earnings trajectory.
Conclusion
The structural indicators—spanning trade deals, budgets, and tax and consumption reforms—point in a very positive direction for a sustained market rally. Even if FIIs delay their return or the market remains volatile short-term, long-term fundamentals remain intact. Foreign investors are ultimately driven by profit; once Indian valuations make undeniable sense relative to growth, foreign capital will inevitably return to the Indian stock market. If you want to dive deeper into these investment insights, let me know: