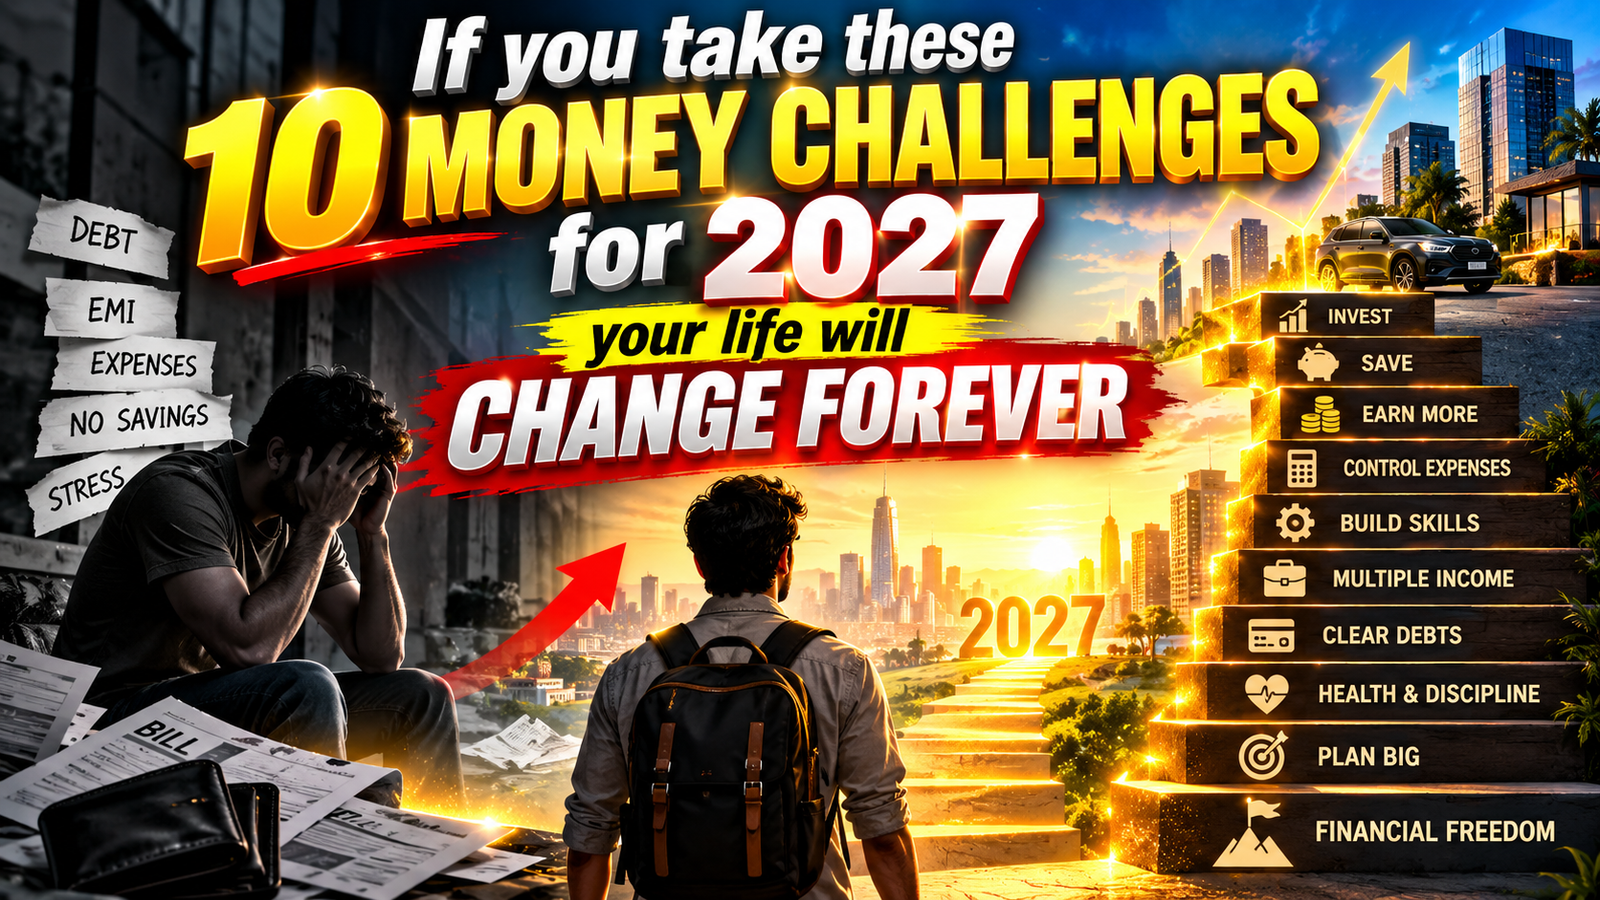
Hi friends, you’re going to thank me for this video. Why? Because in this video, I’m going to share with you 10 money challenges that I’ve set up for myself for 2027. I can write on a stamp paper that if you also take up these 10 money challenges, by the end of 2027, your money life will completely change. The reason I’m so confident is because these 10 money challenges are difficult—in fact, very, very difficult. They are so difficult that 99% of people don’t even think about them. So, are you ready to take up these challenges?
Challenge 1: Increase Your Net Worth by 25%
Let’s start with number one. The first money challenge is to increase your net worth by 25%. Now, what is net worth? Net worth is simply assets minus liabilities. What are assets? Assets are everything that you own: for example, your mutual fund portfolio, your stocks, your gold, your plots, your car, etc. Liabilities are things that you owe: for example, your EMIs, your home loan, your credit card loans, or whatever loans you have. Net worth is very, very important, and I’ll explain to you why in a minute.
But before that, let us assume that your current net worth is 1 crore. The challenge here that we are taking up is that by the end of 2027, this 1 crore needs to go up to, let’s say, 1.25 crore. Now, 25% is the target I have set up for myself. You might want to adjust this according to your situation; I’m not saying that it has to be 25%, but in my case, I have set it up for 25%.
Why am I stressing about net worth so much? There are three reasons. Number one is that 99% of people don’t even have a clue about what their net worth is right now. In fact, right now, if I ask you what your net worth is, you’ll be clueless. This is simply because some money is lying with relatives, some money is lying in some crypto app that you’ve not even opened in the last two years, or your assets are scattered across various places. You have no idea how much your total assets and liabilities are, so this will force you to first go and calculate your net worth.
The second reason net worth is the most important thing is because it doesn’t matter how much you earn, how much you spend, or how much you invest—what really remains with you is your net worth. For example, if your income goes up by 10% and you put that money in F&O and lose it, that earning did not matter because it did not stay with you. You earn money, you spend money, and you invest money, but what remains with you is wealth. That is the difference between wealth and money. The entire idea of this challenge is to make sure we understand what our net worth is and grow it by 25% by the end of 2027.
Coming to the third reason why I have set net worth as my first challenge, it is because it will force you to think through all angles. In order to grow your net worth, you will have to look at your income and try to increase it, rationalize your expenses wherever possible, and look at your investments to see if they are growing at the right speed to hit your target number. What I want you to do is write down in the comments that you are accepting challenge number one, and write down your personal target. Do you want to take up 25%, 10%, 5%, or 50%? It doesn’t really matter. What really matters is that you are taking this up as a challenge along with me, and by 2027, if you hit this challenge, you’re going to thank me.
Challenge 2: Explore an AI-Proof Business Idea
Let’s go to number two. The second money challenge is to explore a new business idea that can completely replace your current income. For example, in my case, I’m going to add a new business line, and my target is to generate around 5 crores annually from that new line. I know that could be very, very difficult for many of you, but hear me out. Just a few days back, Reuters published a list of companies that have announced job losses or layoffs from October 2025, and this is a very long list. I’m not trying to scare you at all, but this is a realistic picture that is going to play out in the next two to three years. For example, if you’re working in the IT sector, banking, or private sector jobs, it is entirely possible that in the next two to three years, because of AI adoption, some of these jobs start to disappear, and you have to have a Plan B.
One of the good ways to start thinking about businesses is to use 2026 to prepare so your challenge in 2027 will be to just explore one business idea that can replace 80 to 90% of your income. However, this business has to be an AI-proof business. Now you’ll ask me, “Rahul, what are the AI-proof business ideas?” I’ll give you two or three right away.
Number one is an Airbnb business. This is largely AI-proof, and in fact, it is a business that you can start with very limited capital, even part-time, and there is good profitability in it. If you want to understand the nitty-gritty of this business, I’ve done two podcasts on my “Good to Great” channel. The first podcast I did was with Kartik Anand, who left his job at around 23 and started doing the Airbnb business full-time, and he’s doing wonderfully. Go and watch that podcast first because it will give you a starting point. The second podcast I did was with Aditya Parashar, and this one focuses on how to scale your Airbnb business. Aditya has scaled his business to more than 250 plus properties, so please go and watch that podcast to learn a lot about scaling.
Now comes the second business idea, which is to start looking at and exploring some franchise business ideas. For example, I did a recent podcast on the laundry business. It’s an absolutely boring business, but it is totally AI-proof. Go and watch this video; you’re going to learn how much initial investment you need, whether you can start it part-time, what the profit margins and total revenues are, and what the risks are. We have explained everything in that particular podcast.
The third business idea is the solar business. Now, this podcast is not yet released on my channel; it’s going to be released in the next one to two days. If you have not yet hit the subscribe button on the “Good to Great” channel, please do so. I’m going to bring crazy business ideas in the next few months that you can explore along with me. Solar businesses have four to five different business models that do not need a lot of money. A lot of people think that solar businesses need a lot of upfront investment, but it doesn’t really. We have broken that down with someone from Bihar who has done 1,000 crores of revenue in the last few years—mind-boggling progress that I’m going to present to you in that podcast. Please go and subscribe so that you can continue to increase your money game.
So, this is the second challenge that you’re going to take up: to explore a business idea that has the potential to replace your income. I’m not saying that you have to replace your income in 2027; no, the 2027 challenge is just to explore one business idea that has the potential to completely replace the income you are earning today. This is my money challenge that I’m setting up for myself: 5 crores yearly revenue is what I want to generate in addition to what I’m doing today with a new business line, and hopefully, I’ll announce that very soon when I’m ready. If you’re liking this video so far, I request you to hit the like button and let me know in the comments if you’re taking up any of these challenges. I want to see how many people are interested so I can break down these topics in greater length later.
Sponsor Message: Odoo Accounting
Before I move to the next money challenge, I want to thank the partners of this video, Odoo. When we’re actually running a business, understanding our numbers is just as important as growing revenues. It might seem simple initially, but accounting can become quite complicated as a business grows. There is so much to manage: invoices, expenses, payments, bank transactions, and reconciliations. Suddenly, you’re managing everything across different tools and spreadsheets. This is where Odoo Accounting can help.
With Odoo Accounting, you get a complete accounting system that makes managing your finances much easier and helps reduce manual errors. It also has a bank synchronization feature that helps import transactions automatically, keeping your financial data up to date and accurate. Odoo Accounting also makes financial reporting much easier by generating detailed balance sheets, profit and loss statements, and cash flow reports in just a few clicks. When it comes to taxes, Odoo supports tax regulations across 70 plus countries, which makes tax compliance much more convenient for businesses operating across different markets. I think this is particularly useful for small and growing businesses because you don’t want to spend your time figuring out where a particular number came from; you want to actually understand what those numbers are telling you. So, if you’re running a business and accounting is becoming a little difficult to manage, do check out Odoo Accounting. I’ve put the link in the description, so have a look.
Challenge 3: Diversify Globally
Before I talk about challenge number three, have a look at this data point. You see around 20 economies of the world that have done phenomenally well when it comes to their stock market. For example, look at the US stock market or any other market globally; they have done pretty well, showing 37%, 27%, or 22% YTD from January 2026. Whereas India has done pretty badly—we all know about the 16% downfall in the Sensex. What is this data telling you? It is telling you that it is high time for us to diversify our portfolio and not just limit it to India.
Again, I’m not saying leave the Indian market and go somewhere else just because the Indian market has not performed well over the last two years. In fact, a large proportion of my portfolio will always remain in India—maybe 50%—simply because I live in India, I understand India, the politics, the policies, and the reforms here. I may not understand everything that is happening in global markets, but there are three to four reasons that will force you to think about diversifying globally.
The challenge that I’m taking up is to move around 20% of my portfolio to global markets. Global does not just mean the US stock market; in 2026 itself, I moved around 12% of my portfolio to US stocks, and that money remains in US dollars. I do not intend to bring it back; that money just rotates within the global markets. The reason I’m saying this is because of a few factors, starting with rupee depreciation. Have a look at the rupee; it’s at an all-time low, and very soon, there is a possibility that it could cross 100 rupees versus the dollar. The rupee has been continuously depreciating for 30, 35, or 50 odd years, and we are not protecting our capital from it. The moment you put your INR into USD or any other global currency, you start protecting against depreciation. Whatever percentage you want to send out will not get eroded by rupee depreciation. That is reason number one.
Reason number two is diversification. What if the Indian stock market remains bearish for the next two years? It is entirely possible; the US-Iran war risk is still there at the time of recording this video, and therefore we have to diversify. The third reason is technology. Today, technology allows you to put your money into global markets using solid apps that let you download and transact in seconds. For me, this is non-negotiable for 2027. In 2026, I moved around 12% of my portfolio to the US, and the remaining 8% is going to move in 2027 so that I maintain a 20% allocation in global markets. I will keep around 40 to 50% in India, and the rest of my money will be in gold, real estate, etc. This is how you build an asset allocation strategy.
If you have not yet started global investing, take up a challenge for 2027. You might want to start with 2%, 5%, or 10%—that is up to you—but ensure that you have that goal. If you’re already investing in global markets, I would ask you to think about your exact allocation between global markets and the Indian stock market. I am 100% convinced that if you’re not doing this, you’re making a big blunder in your money management, which is why challenge number three is to go global.
Challenge 4: The Portfolio Cleanup
Let’s move to challenge number four, which is the portfolio cleanup challenge. This is going to be very, very difficult, and there are three things that I am doing.
Number one: before March 2027, review all your loss-making assets. It could be a loss-making stock or a loss-making mutual fund, and you need to really decide whether you want to keep it in your portfolio or not. We accumulate a lot of things in our portfolios—some of which are junk because somebody recommended them. Now is the time in 2027, before the financial year ends and tax benefits kick in, to actually review everything you’ve been holding onto just in the hope that the price will go up. Make a decision. Even if you can’t make an immediate decision, at least have a plan that if the price doesn’t move up by a certain date, you are going to book the losses. It’s okay to book losses because you release capital that can be used for better purposes. I’m going to look at everything that doesn’t make sense from fresh eyes, not just from a price movement perspective, and review whether it belongs in my portfolio.
Number two is cleaning up things that went into your portfolio simply because a relative or a video recommended it to you. Sit down and clean it up. Also, look at your mutual funds that are overlapping. If you have 20 mutual funds, you are likely overlapping heavily, so you have to review that.
The third and most important thing that nobody is talking right now is your asset allocation. Please sit down in 2027 and review where your money is: how much is in gold, properties, cryptos, equities, FDs, and even with relatives. Put all of this together and first measure your asset allocation, then ask yourself if this is the allocation you really want given what is happening in the world. Maybe you want to focus more on debt, corporate bonds, or other instruments. A good practice is to sit down every six months and rebalance your asset allocation. For example, let’s say you had a 20% allocation to gold, but gold prices doubled; the total allocation of gold in your portfolio would have gone up, so you might need to sell some gold to bring it back down to 20%. On the other hand, if your equities are down, it makes more sense to pour some money into equities to maintain your targeted exposure. This is all about asset allocation, and people are not doing it. In 2026, I made a large allocation to the US stock market but didn’t thoroughly rebalance everything else, so in 2027, I’m going to do exactly that. These three steps are part of the portfolio cleanup challenge. You just have to be honest with yourself, sit down with your assets, and mark what you need and what you don’t need. Let me know in the comments which challenges you have taken up so far and what your targets are.
Challenge 5: Invest Based Only on Your Own Research
Let’s move to challenge number five, which is my favorite: investing only based on your own research. You will immediately say, “Rahul, we are already doing it; we only invest where we feel it is a good investment.” In reality, you are getting a lot of influence from the media, YouTube channels, Instagram Reels, etc.
Here is what I’ll tell you: in 2027, whatever investments you make, you have to back them up by writing down five key points on a piece of paper or in a diary.
- First, write down four to five lines explaining exactly why you are picking a stock, a mutual fund, or a cryptocurrency. This will give you insane clarity.
- Second, note at what profit target you want to exit that investment. Right now, we have no clarity; we pick up a stock and have no exit target. You have to clarify your profit expectations.
- Third, write down how long you want to hold this asset. If you want to buy a plot, write down whether you plan to hold it for 2 years or 20 years so you don’t make emotional mistakes.
- Fourth, define what level of volatility you are genuinely okay with. If a stock goes up 10% and then comes down 20%, are you okay with that, or are you going to panic and exit?
- Fifth, you’re not going to make a profit on all assets—I can guarantee that—so write down the maximum loss you can afford to tolerate on that particular asset.
If you write down these five things for, let’s say, 10 investment calls in 2027, you can go back and reflect in 2028. You can review your plan and check if you actually stuck to it. You will often find that your actual behavior is very different from your initial intentions, and this process allows you to fix it. There are no quick fixes in this world when it comes to money; you really have to put in the effort. If I just tell you to buy or sell a specific stock, it doesn’t help you long-term; you have to fix your own financial behavior. This challenge is something I am strictly doing for myself: every investment call I make in 2027 will be backed by these five points written in a diary. It’s a small step but very powerful. If you’re taking this up, write down, “Rahul, I’m taking up challenge number five.” A lot of effort goes into these practical aspects; these are not copy-pasted from ChatGPT or Claude, but are things I’ve learned from making mistakes over many years.
Challenge 6: Zero Lifestyle Inflation
With that, let’s go to number six: zero lifestyle inflation. Let me explain with an example. Let’s say in 2026, your total income is 20 lakh rupees per year, and your expenses are 15 lakhs per year. In 2027, let us assume that your income goes up because you got a salary hike, a bonus, or profits from stocks, taking your income from 20 lakhs to 25 lakh rupees per year. The challenge you are going to take up is that your expenses should remain at 15 lakhs per year, adjusted only for normal inflation. Meaning, your lifestyle should remain exactly similar for one year.
I’m not saying you cut down on your current comforts; if the prices of things you already consume go up, that’s absolutely fine, and you continue to consume them. You’re not compromising on your existing lifestyle, but you are choosing not to upgrade it for just one year despite the higher income. The moment income goes up, the first thing people do is spend all of that extra money away, so their net worth never gets a chance to grow. If you earn an extra 5 lakh rupees in 2027, let it sit and invest it for at least one year before you upgrade your lifestyle.
Personally, there are two things I’ve wanted to upgrade but won’t touch in 2027. My iPhone 14 has been with me for a number of years, and though I wanted to upgrade, I’m going to wait another year. My Tata Nexon car has been with me for over 3 years; I wanted to upgrade it in 2026, but I’m holding off through 2027 because I want to allocate capital into real estate instead. After 2027, I will be free to upgrade my car and mobile. As I said in the beginning, these challenges are hard, but I am doing them because I have a strict plan to become financially free by 2030, and staying on target requires doing hard things.
Challenge 7: Spend Money on Your Own Learning
Let’s move to number seven: spending money on your own learning. For 2027, I’ve set a target to spend around 10 lakh rupees on my own education and growth. This number might sound very high, but I do not have a lot of other personal expenses, and this is the one major area I invest in every year. In 2027, I am doubling it to 10 lakhs to focus on three distinct things.
Number one: deeply learning technical analysis of stocks. I know the basics, but I want to go deep into it in 2027. Number two: improving at networking events. I am historically very bad at networking and rarely attend events, so my brand manager is going to push me to attend them in 2027. Number three is personal branding, because I genuinely believe your personal brand is the only thing that will remain completely AI-proof in the future. I am okay spending 10 lakhs because it involves travel, shoots, and high-quality courses.
For you, the challenge is simply to set up a small learning budget. The reason I say you should allocate actual money is that if you rely purely on free content, you often don’t value it or stay structured and focused until you have some skin in the game. There is no denying you can learn from free resources, but when you spend money, make sure it is for structured quality. Pick just one area you’ve been putting off improving for years and use 2027 to master it with me.
Challenge 8: The Couple Money Challenge
Let’s move to number eight, which is the simplest of all: the couple money challenge. If you’re married, sit down with your spouse; if you’re not married, sit down with your partner, and openly talk about your financial goals. Discuss simple things like your expenses, your investments, and where your income is heading. It will help you honestly share worries with each other. For example, if there are layoffs happening at the husband’s office, he needs to sit down and share that with his wife so they can build a financial plan together.
I highly recommend doing this at least once a quarter—four times a year. Sit down and discuss how changing dynamics, like rising fuel costs, are impacting your household budget. These conversations will help you bond, bringing honesty and clarity to your relationship. It takes just 20 to 30 minutes each quarter, yet very few people do it consistently.
Challenge 9: The Financial Document Challenge
Let’s go to number nine: the financial document challenge. This is also very easy. The step you need to take is to create a large physical folder and compile all your essential documents: your PAN card, insurance policies, home loan documents, annual statements for all your Demat accounts, and yearly bank statements. This physical folder becomes the holy grail of your finances.
It should be easily accessible to your spouse, partner, or children so that they know exactly what to do in case of an emergency. More importantly, if anything ever goes wrong digitally with your accounts, you have a physical audit trail right in front of you to save time and effort. Please print everything out and put it in a physical folder in 2027. I know it sounds like taking you back to the 1980s, but in an increasingly digital world, having physical access to your financial blueprint is critical and brings attention to matters you might have overlooked.
Challenge 10: Register Your Will
Before I go to number 10, please remember to share this video on WhatsApp with your family and friends so everyone can benefit from these habits, even if they only choose to pick a few challenges.
Number 10 is to get your will registered. There are several benefits to this, but the core reason is that if you do not have a registered will in place, the law will dictate what happens to your assets after you are gone. For example, Hindus, Buddhists, Sikhs, and Jains are governed by the Hindu Succession Act of 1956; Muslims are governed by Islamic Personal Law; and Christians and Parsis are governed by the Indian Succession Act of 1925. If you do not want the law to decide the fate of your hard-earned wealth, you must draft a will and get it registered. This ensures absolute peace, clarity, and zero legal hassles or fights among family members later on. Number 10 is very easy, it just requires execution in 2027.
Conclusion
There you go—these are the 10 money challenges. I want you to write down in the comments which challenge you found the most interesting, which one seems the most difficult, and which one is the easiest for you to start. Once again, thank you to the partners of this video, Odoo; the link is available in the description and pinned comments. If you liked this video, request you to hit the like button and subscribe to my channel. I’m going to see you in my next video. Until then, keep rocking!