Hi friends, my name is srikrishna. Recently, you might have seen an advertisement for a new fund offer by an asset management company launching an index fund on the capital market theme. The reason I am showing you this is that if you ask me which single theme I am most bullish about for 2040, I would say the capital market theme. I have three big, data-backed reasons for this.
The Surge in Indian Stock Market Volumes
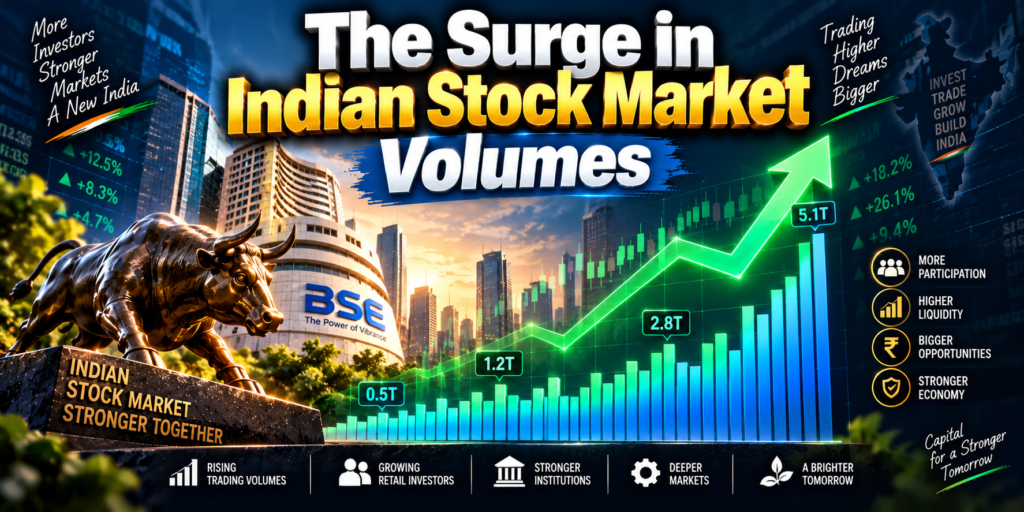
The first reason is the sheer volume of transactions happening in the Indian stock market. Since FY16, equity volume has grown at around a 23% CAGR. Furthermore, derivative volume (Futures & Options) has grown at an astronomical 67% CAGR since FY16, showing massive vertical growth heading into FY24 and FY25.
Can this trend continue to sustain? Absolutely. Equity investments currently account for only about 6% of household assets in India. Compare this with the USA, where it stands around 22%, and you can see there is still massive room for growth in Indian stock market volumes. The direct beneficiaries of this growing volume will be brokerages, exchanges, depositories, and asset management businesses.
Rising Demat Account Penetration
The second important reason is the rapid growth of Demat accounts. Over the last five to six years, new Demat accounts have grown at around a 33% CAGR. Yet, as of FY25, only 13% of the Indian population holds a Demat account. This means more than 80% of the population has not yet entered the market. Imagine the compounding growth for the next 15 to 20 years when even half of that remaining population decides to open accounts.
Mutual Fund and SIP Growth Ecosystem
The third reason is the steady growth of Systematic Investment Plans (SIPs). Since FY16-17, the growth rate of SIP contributions in the Indian stock market has been around 26%, seeing a massive surge through FY25 and FY26. Even with this excellent trajectory, India’s mutual fund Asset Under Management (AUM) to GDP ratio sits at a modest 20%, whereas the US stands at around 124%.
While the capital market theme will experience natural cyclicity—meaning exchange transactions will occasionally drop and trigger corrections—these pullbacks are excellent buying opportunities for long-term investors.
Exploring the Nifty Capital Market Index Fund
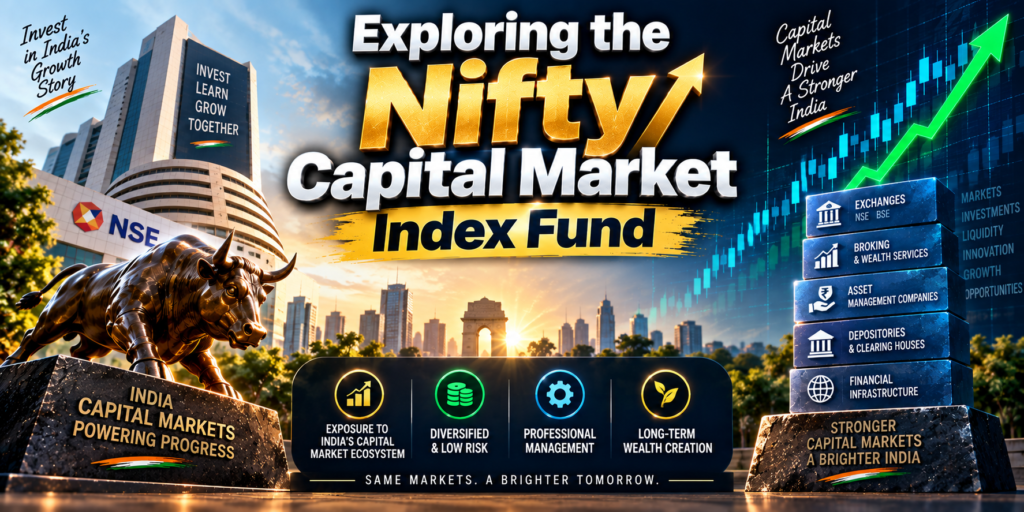
If you do not want to pick individual stocks, the first approach is to rely on index mutual funds tracking the Nifty Capital Market Index. Looking at the current allocation of this index, exchange and data platforms make up about 40%, asset management companies account for 23%, stockbroking represents 19.5%, and depository clearing houses comprise 13.5%.
From a market cap perspective, it is heavily mid-cap driven at 54%, followed by small-caps at 29% and large-caps at 15.9%. This heavy mid and small-cap exposure makes the index highly volatile and unsuitable for conservative investors. As of now, the top allocations by weight feature BSE at 19.8%, MCX at 17%, and HDFC AMC at 13%. Looking at historical annual returns as of March 30, 2026—right around a market correction caused by a geopolitical war situation—the index delivered 25.4% over the last year, 58% over three years, 31.9% over five years, and 24.6% since its 2019 benchmark inception.
Deep Dive Stock 1: Bombay Stock Exchange (BSE) Limited
For those looking at individual stocks, our first focus is Bombay Stock Exchange Limited. Looking at financial data since the COVID period in FY20, BSE shows an incredibly consistent pattern: top-line revenue has grown at a 34% CAGR, while net profit has scaled at a 60% CAGR. Their net profit margin expanded drastically from 14% in FY20 to roughly 48% in FY26. Because an exchange has high fixed costs, additional transactional volumes flow almost entirely into improving operational margins.
Transaction charges make up 73% of BSE’s top line. Breaking that down further, equity cash contributes only 5% of revenue, while equity derivatives (F&O) drive a massive 60% of the top line. Despite recent anxieties regarding an increase in Securities Transaction Tax (STT) starting April 1st, BSE has actually gained market share over NSE due to its lower relative pricing structure, with volumes remaining highly robust. Management also plans to scale up commodity trading and stock options in the future.
Valuation-wise, BSE is trading at a P/E ratio of around 63, against a 3-year median P/E of 69. Given its growth profile, a P/E closer to 50 to 52 would represent a much more comfortable entry level. Keep in mind that its primary competitor, NSE, currently trades around a 40 P/E in the unlisted market and is expected to list around Q3 2026. NSE’s eventual listing might create temporary pressure on BSE as they compete for investor attention, but those regulatory or volume-driven price dips should be viewed as long-term opportunities.
Deep Dive Stock 2: Groww
The second company is on the broking side: Groww, which listed in November 2025 with a 14% premium at a listing price of 114 on BSE and 112 on NSE. At the time of its IPO, its P/E ratio was around 40 with a Price-to-Book (P/B) ratio of 11.76. Currently, the P/E has shot up to 62 and the P/B sits at 13.5.
This valuation jump is backed by massive Q4 year-on-year growth: total income rose by 81%, EBITDA jumped by 142%, and Profit After Tax (PAT) surged by 122%. Transacting users also scaled up by 25%. Due to strong operating leverage, their cost to serve has decreased, pushing EBITDA margins from 50% up to 66%. Like BSE, Groww relies heavily on the F&O segment, which brought in 55% of its Q4 FY26 revenues. Groww is diversifying aggressively by launching commodities, primary and secondary bonds, growing its mutual fund AUM 2.5 times in a single year, and acquiring the wealth management firm Fisdom. While a P/E of 60 is high, it remains justified if the company continues to sustain near triple-digit PAT growth.
Deep Dive Stock 3: Asset Management Companies (ICICI vs. HDFC)
Looking at the Asset Management Company (AMC) sector, SBI Mutual Fund remains the unlisted leader with a target listing window in late 2026. Behind them sit ICICI Prudential AMC at a 13.5% market share and HDFC AMC at 12.5%.
Comparing the two listed giants in FY26, ICICI’s top line grew by 20% and PAT grew by 24.5%. In contrast, HDFC’s top line grew by 14% and its PAT grew by 16%. While both share a similar operating profit margin profile of around 35% to 37%, ICICI boasts a significantly superior Return on Equity (ROE) of 85% compared to HDFC’s 32.9%.
SIP inflows across all AMCs have grown at a very healthy pace over the last three years as retail investors shift away from traditional fixed deposits and gold. However, looking at valuations, ICICI trades at a premium P/E of 48 while HDFC trades at 42. With a profit growth rate of 24%, ICICI’s PEG ratio pushes above one. Personally, I am less comfortable buying AMCs at these current elevated levels compared to the explosive growth seen in the exchange and brokerage sectors. If a market correction or geopolitical event drops AMC stock prices by 20% to 25% and cools down the P/E ratios, that would be the ideal time to evaluate them. The ecosystem will become incredibly interesting to track once SBI lists later in 2026.
Conclusion
To summarize, if you are hesitant to select individual stocks, look into a capital market index fund. Over a 20-year horizon, this sector enjoys massive macro tailwinds alongside other high-growth spaces like data centers and semiconductors. Thank you for watching, and don’t forget to keep learning. Until next time, keep rocking!